Imagine you bought a token last year because it looked like the next big thing. You held it, maybe staked it, and now you're wondering if you actually own a piece of a company or just a digital receipt for future utility. This isn't just a philosophical puzzle; it's a legal minefield that determines whether your gains are taxed as capital income or ordinary income, and whether the government can freeze your assets without warning. As of late 2026, the question are cryptocurrencies securities remains one of the most expensive and confusing issues in finance.
The short answer is: it depends. But "it depends" is rarely helpful when you have $50,000 on the line. The reality is that regulators don't look at the word "crypto." They look at what the token actually does. If you put money into a project expecting profits primarily from someone else's hard work, you likely bought a security. If you bought a coin to use its network features, you likely didn't. The difference between these two outcomes can mean millions in fines for companies and sudden delistings for investors.
The Rulebook: Understanding the Howey Test
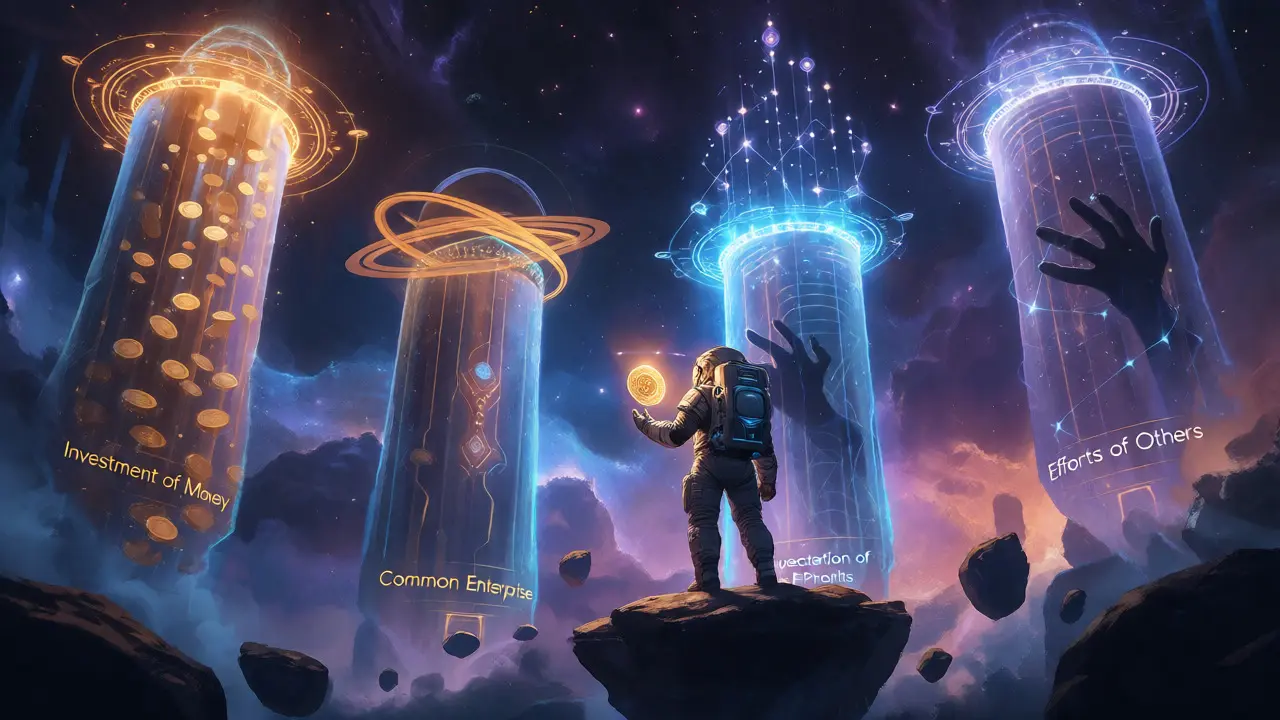
To understand why Bitcoin is treated differently than a random altcoin, you need to know about the Howey Test. It is a four-part test established by the U.S. Supreme Court in 1946 to determine if a transaction qualifies as an "investment contract". Despite being nearly 80 years old, this test is still the primary tool the SEC uses to judge modern digital assets.
Here is how the test breaks down in plain English:
- Investment of Money: Did you give up cash (or other value) to get the token?
- Common Enterprise: Is your success tied to the success of others? Do you pool resources with other investors?
- Expectation of Profits: Did you buy it hoping the price would go up so you could sell for a profit?
- Efforts of Others: Is that profit coming mostly from the work of a central team, developers, or managers, rather than your own efforts or market forces alone?
If the answer to all four is "yes," the SEC considers it a security. This is where things get tricky for blockchain projects. Many early tokens were sold to fund development. Investors gave money to a centralized team, expecting that team to build a product that would make the token valuable. That fits the Howey Test perfectly. However, if a network becomes fully decentralized-meaning no single group controls it-the "efforts of others" prong might fail. This is often called the "decentralization defense," though the SEC doesn't always accept it easily.
Bitcoin vs. Ethereum: Why Are They Different?
You might ask, "If Bitcoin was sold to people who expected profits, why isn't it a security?" Good question. The CFTC, which regulates commodities, has classified BTC as a commodity. The logic here relies on the concept of sufficient decentralization. Because there is no CEO of Bitcoin, no marketing department pushing ads, and no central foundation promising returns, the profit comes from global adoption and scarcity, not the "entrepreneurial efforts" of a specific group.
Ethereum sits in a gray area. For years, the SEC debated its status. In September 2022, former CFTC Chair Rostin Behnam and then-SEC Chair Gary Gensler jointly testified that both Bitcoin and Ethereum should be treated as commodities. This was a massive win for the industry. However, this doesn't mean every token on Ethereum is safe. Just because the road is public doesn't mean every car driving on it is registered. Most ERC-20 tokens launched on Ethereum are still scrutinized under the Howey Test individually.
The Enforcement Era: What Happened When Rules Were Broken
Between 2017 and 2026, the SEC shifted from watching to striking. They didn't just write guidelines; they sued. Look at Ripple Labs. The SEC sued them in 2020, claiming their XRP token was an unregistered security. The case dragged on for years, costing millions in legal fees. In July 2023, a judge ruled that XRP sales on exchanges were not securities offerings, but institutional sales were. This split decision confused everyone and left the final outcome pending until late 2026.
Other cases were less ambiguous. Kik Interactive settled for $100,000 after selling its Kin token. Telegram had to return $1.2 billion to investors because their Gram tokens were deemed securities before the network even launched. These weren't minor slap-on-the-wrist moments. They were existential threats to startups.
Even stablecoins aren't immune. While fiat-backed coins like USDC are generally seen as payment instruments, algorithmic ones face heat. When TerraUSD collapsed in May 2022, wiping out $40 billion, regulators pointed to the lack of collateral and the reliance on a central team's management as signs of security-like risks. By January 2026, the SEC had settled with Paxos for $150 million over its BUSD stablecoin, proving that even "stable" assets can trigger securities laws if the structure looks like an investment contract.
Utility Tokens vs. Investment Contracts
Most crypto projects call themselves "utility tokens." They argue you buy the token to use the software, not to invest. Think of it like buying a ticket to a theme park. You buy the ticket to ride the rides, not because you expect the ticket price to triple next year. If the primary purpose is consumption, it’s usually not a security.
But here is the catch: marketing matters. If a project screams "Buy now! Price going to the moon!" while selling a utility token, the SEC argues that the expectation of profit overrides the utility. A famous example is Munchee Inc., which tried to launch a utility token for a food review app. The SEC shut it down in December 2017 because the marketing promised profits from the company's efforts, not just access to reviews.
So, how do you tell the difference? Look at the smart contract code and the whitepaper. Does the token pay dividends? Does it grant voting rights on corporate decisions? Does it require a central team to maintain the value? If yes, you’re probably holding a security.
| Asset Type | Primary Regulator | Key Characteristic | Security Status |
|---|---|---|---|
| Bitcoin (BTC) | CFTC | Fully decentralized, no central issuer | Commodity |
| Ethereum (ETH) | CFTC / SEC (Gray Area) | Decentralized but with active core dev influence | Generally Commodity |
| XRP (Ripple) | SEC (Litigation Ongoing) | Centralized supply, institutional sales | Mixed (Not security for retail exchange sales) |
| ERC-20 Utility Tokens | SEC | Access to platform, often marketed for profit | High Risk of Security Classification |
| Stablecoins (USDC) | State/Fed | Pegged to USD, redeemable | Payment Instrument |
The Cost of Uncertainty for Investors and Startups
This regulatory fog isn't free. According to a CoinDesk survey from January 2026, 68% of crypto startups delayed or canceled token launches because they couldn't figure out if they'd get sued. Forty-two percent specifically cited fear of SEC enforcement. This uncertainty drives innovation overseas. Between 2023 and 2025, 31 major U.S. crypto projects moved operations abroad, taking an estimated $4.7 billion in investment with them to jurisdictions like Singapore and Switzerland.
For you, the investor, this means risk. If a token is deemed a security retroactively, your exchange might delist it. Remember Kraken? In February 2023, they paid $30 million to settle charges that their staking service was an unregistered securities offering. Users lost access to certain staking rewards overnight. Coinbase reported spending $109 million on compliance in Q1 2025 alone. Those costs often trickle down to users via higher fees or fewer available pairs.
There is also the tax nightmare. If your asset is a security, different reporting rules apply compared to commodities. Misclassifying it can lead to audits. One Reddit user noted having to liquidate an $85,000 DeFi position because the SEC cracked down on similar platforms, killing exit liquidity. You didn't lose the tech; you lost the ability to sell because the legal status made buyers nervous.
What Comes Next? The Path to Clarity
Is there light at the end of the tunnel? Maybe. In January 2026, Senator Cynthia Lummis introduced the Responsible Financial Innovation Act. It aims to create clear criteria for what counts as a digital commodity versus a security. If passed, it could end the guessing game. Meanwhile, the SEC approved spot Ethereum ETFs in March 2025, tacitly accepting ETH's commodity status despite earlier skepticism.
International bodies are also weighing in. The International Organization of Securities Commissions (IOSCO) recommended in late 2025 that countries focus on "economic substance" rather than technology labels. This suggests a move toward a more nuanced approach where a token's function dictates its regulation, not its blockchain origin.
Until then, assume everything except Bitcoin and Ethereum is potentially a security until proven otherwise. Read the whitepapers. Check if there is a central team controlling the funds. And keep an eye on the Ripple case, whose final ruling in Q3 2026 could set the definitive precedent for the entire industry.
Is Bitcoin considered a security?
No, Bitcoin is generally classified as a commodity by the CFTC and SEC. This is because it is fully decentralized, meaning no single entity or group is responsible for its success, failing the "efforts of others" prong of the Howey Test.
Why did the SEC sue Ripple Labs?
The SEC argued that Ripple sold XRP as an unregistered security. They claimed investors bought XRP expecting profits derived from Ripple's entrepreneurial efforts. The court ruled that retail sales on exchanges were not securities, but institutional sales were, leaving a complex mixed status.
What is the Howey Test?
The Howey Test is a legal standard used to determine if a transaction is an "investment contract" (a type of security). It checks for four elements: investment of money, a common enterprise, an expectation of profits, and profits derived from the efforts of others.
Are stablecoins securities?
Most fiat-collateralized stablecoins like USDC are treated as payment instruments, not securities. However, algorithmic stablecoins or those with yield-bearing features may face scrutiny under securities laws if they promise returns based on managerial efforts.
How does decentralization affect security status?
If a network is sufficiently decentralized, it may cease to be a security because profits are no longer derived from the "efforts of others" (a central team) but from the collective action of the community and market dynamics. This is known as the "decentralization defense."


I'm a blockchain analyst and crypto educator who builds research-backed content for traders and newcomers. I publish deep dives on emerging coins, dissect exchange mechanics, and curate legitimate airdrop opportunities. Previously I led token economics at a fintech startup and now consult for Web3 projects. I turn complex on-chain data into clear, actionable insights.